You Don't Own a Salon. You Own A Business.
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
 MENU
 SEARCH
Both HSAs and FSAs offer valuable tax advantages and can significantly reduce the financial burden that comes with healthcare costs. Find out the difference between the two and how they may benefit both you and your employees.
Azarvand Tax Law's Leticia Skrabut shows you Health Savings Accounts and Flexible Spending Accounts can save you on healthcare costs, while giving your employees a valuable benefit.
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) are financial tools designed to help individuals manage healthcare costs. Both are pre-tax benefit programs that can help your team pay for medical expenses while reducing their tax bills. Offering these benefits can be a powerful tool for attracting and retaining stylists, colorists, and support staff. You save on payroll taxes, and your employees save money on healthcare.
Salon workers face unique physical demands throughout their careers. The standing, repetitive motions, and exposure to chemicals create specific health needs that both HSAs and FSAs can help address. These accounts may cover work-related health expenses like podiatrist visits for foot pain, custom orthotics and arch supports, wrist braces for carpal tunnel, physical therapy and massage therapy, prescription safety glasses for color work, contact lenses and solution, LASIK and vision correction surgery, therapy and counseling sessions, stress management programs, prescription medications, doctor visit copays, and dental and orthodontic work.
One effective way to offer these benefits is through a Section 125 plan. This arrangement allows employees to elect pre-tax contributions to an HSA or FSA during annual enrollment. Contributions are deducted from wages before taxes, reducing taxable income and increasing take-home pay. Employers also benefit from reduced payroll taxes, while employees save on income and payroll taxes. Participation in either account is optional, and employees can choose whether or not to enroll, similar to how they might opt in or out of a health insurance plan.
FSAs are employer-owned and subject to the "use-it-or-lose-it" rule, meaning unused funds are forfeited and returned to the employer at the end of the year (with no tax benefit), though some plans offer a grace period or limited carryover. These accounts are typically offered as part of an employer-sponsored benefits package, with contributions made through payroll deductions. Employers may also contribute to FSAs depending on the plan design. FSAs do not earn interest and are not portable, meaning they are forfeited if employment ends. The 2025 contribution limit for healthcare FSAs is $3,300. FSAs also support dependent care expenses, which can be helpful for employees with young children.
HSAs, by contrast, are employee-owned, portable, and allow unused funds to roll over annually, providing a sense of reassurance and adaptability. Money in an HSA earns interest, can be invested, and remains with the individual even after job changes. To be eligible for an HSA, individuals must be enrolled in a high-deductible health plan (HDHP). For 2025, an HDHP is a plan with a minimum deductible of $1,650 for individuals and $3,300 for families. The out-of-pocket maximums are $8,300 for individuals and $16,600 for families. These thresholds help determine whether someone is qualified to open and contribute to an HSA.
Contributions can come from the account holder, employers, or third parties. For 2025, contribution limits are $4,300 for individuals and $8,550 for families. Individuals aged 55 and older can contribute an additional $1,000. If a salon does not offer a high-deductible health plan, FSAs may be the more practical option. HSAs require enrollment in an HDHP and compliance with additional IRS requirements, including restrictions on Medicare enrollment and dependent status.
HSAs offer a powerful triple tax advantage that makes them particularly attractive for long-term financial planning. First, contributions are tax-deductible and do not need to be itemized. If you contribute to your HSA through automatic payroll deductions, those pre-tax dollars reduce your taxable income. If your employer also contributes to your HSA, those funds are excluded from taxable income. Second, money in an HSA earns investment interest and grows tax-deferred, meaning that tax does not need to be paid while the money remains in the HSA. Third, withdrawals from HSA funds to pay for qualified medical expenses are tax-free and can be made at any time without penalty.
FSAs, while still beneficial, offer a single tax advantage, which is pre-tax contributions that reduce taxable income. This distinction makes HSAs attractive for employees who want to build long-term healthcare savings, especially as they approach retirement. HSAs also function as a retirement savings vehicle. After age 65, funds can be withdrawn without penalty for any purpose, not just medical expenses, though regular income tax applies. Additionally, many HSA providers offer investment options, allowing account holders to grow their savings over time. This makes HSAs a unique blend of healthcare and retirement planning.
Both HSAs and FSAs can be used to pay for a wide range of qualified medical expenses and to cover healthcare expenses for dependents, not just the account holder. This might include prescription safety glasses, ergonomic chairs, or mats to reduce work-related strain, mental health services, and even chiropractic care. Employees typically elect their contributions during annual enrollment periods. However, certain qualifying life events such as marriage, birth of a child, or loss of other coverage may allow mid-year changes to FSA or HSA elections.
Both HSAs and FSAs offer valuable tax advantages and can significantly reduce the financial burden that comes with healthcare costs. To determine whether an HSA, FSA, or a combination is best for your salon business and your team, you can book a complimentary 30-minute consultation online at AzarvandTaxLaw.com or by sending us an email at Info@AzarvandTaxLaw.com.
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
In her latest blog, Amy Pal helps you develop your own clear guidelines around complimentary free employee services.
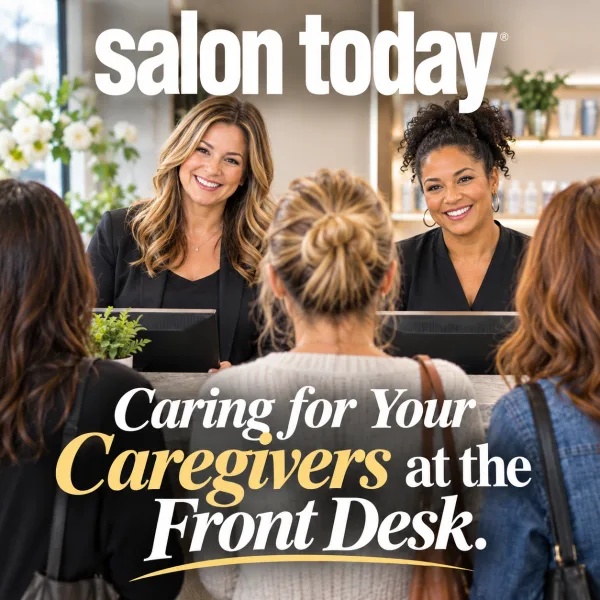
From managing air traffic on busy days to handling frustrated guests' complaints, your front desk team often serves as the salon's emotional shock absorber. From a customer service lesson from the DMV to a list of strategies for caring for your front line, our experts offer ideas for alleviating stress, celebrating wins, and setting goals.
According to the KIM Report, top-line salon revenue appears steady or slightly up, but that growth is driven primarily by service price increases. Beneath the surface, retail performance and client visit frequency (appointment drift) are under real pressure. In his latest blog, Alain Audet offers strategies for keeping your salon's retail sales strong.
Putting your family to work in the salon offers some real tax benefits, but you have you have to play by the rules of the tax code to claim them. Azarvand Tax Law's Leticia Skrabut, Esq., shows you how.
Discover how to create a true “WOW experience” for every client by first building a culture where your team feels engaged, empowered, and inspired. Drawing on Calvin Stovall’s Iconic Framework, this blog explores how salon, spa, and clinic leaders can strengthen culture, elevate customer experience, and build a business that stands out for the long term.
Sponsored by Phorest Salon Software
The wellness industry is growing fast, and salons and barbershops already are an important part of it. In her first blog, Tracy Rado shares where the wellness dollars are heading, and how salons can grow with this movement.
While salon sales are increasing, owners often feel they're working harder for the same or less profit. Leverage Q2 data from The KIM Report, Alain Audet reveals some of the structural changes that are dampening your growth and why your region and your salon size matters.
Weaknesses in your business are amplified during the Holiday Season. Spark Pro Global's Lucy Randall shows you five things to do now to have the strongest holiday season yet.

In Kati Whitledge's latest blog, she shares how salons have moved away from dress codes and embraced appearance standards. But by removing strict dress codes, some businesses may have unintentionally lowered their appearance standards. Whitledge helps you explain to your team why an appearance standard is important and how to smoothly implement a new appearance policy.
The Small Business Health Care Tax Credit is a non-refundable tax credit for for-profit businesses that provides a financial incentive for eligible employers who offer health insurance coverage to their employees. Leticia Skrabut, Esq., walks you through how to claim that credit.
Developing strong work habits early in one's career supports long-term success in the salon industry. Jesse Linares offers new stylists his top five tips.
Most salon owners have no idea what these numbers are. You can hit record sales and still have a profit problem. The difference comes down to four numbers almost nobody was taught to track.
Sponsored by Strata Salon Systems™
A five-area audit every owner-dependent salon needs to run. You built something that looks successful. Now find out if it can survive without you.
Sponsored by Strata Salon Systems™
Every month you put off fixing the problem, it gets bigger, more expensive, and harder to solve.
Sponsored by Strata Salon Systems™
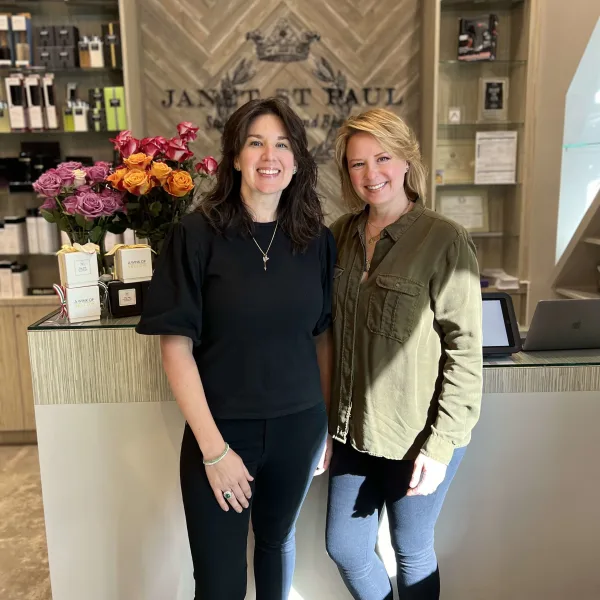
At Janet St. Paul Studio for Hair and Beauty, Director of Operations Natasha McMillen helps bring her wife Janet St. Paul's vision to life, elevating every system from education to operations.
Expand your color service menu with the Pinstripe technique. Brooks and Brooks' Marlon Hawkins walks you through the technique.