


You Don't Own a Salon. You Own A Business.
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
 MENU
 SEARCH
Buying business insurance may seem complicated, but it doesn’t have to be. Still, the insurance business seems to have a language of its own. What’s the difference between General Liability and Professional Liability? And what is E&O? I’m a business owner – does that mean I need a Business Owner’s Policy?
*This article was repurposed with permission from Hiscox.
By: Karen Doyle
Buying business insurance may seem complicated, but it doesn’t have to be. Still, the insurance business seems to have a language of its own. What’s the difference between General Liability and Professional Liability? And what is E&O? I’m a business owner – does that mean I need a Business Owner’s Policy?
Here’s an easy way to find out what you need. Just answer these six questions, and we’ll show you what kind of coverage can help keep your business well protected.
1. Do you operate from your home, a space you don’t own, or a client’s premises?
If so, you need General Liability insurance, the basic coverage that every business needs. General Liability covers third-party claims of property damage, bodily injury, and more. So if someone (other than yourself or an employee) says you damaged their property or caused them to be injured, your General Liability policy could cover the cost to repair or replace the damaged property, or pay for their medical expenses, including lost wages.
2. Do you own the commercial building you operate from?
If so, a Business Owner’s Policy (BOP) will cover your business premises and property, in addition to providing the third-party coverage of General Liability coverage. If your building – and your property inside it -- is damaged, a BOP could cover the cost to repair it and get you back to work.
3. Do you have business equipment (computers, furniture, tools, etc.)?
If you have equipment that you rely on to get your work done, consider a Business Owner’s Policy (BOP). This includes General Liability coverage, plus first-party coverage for your own business property. Suppose your computers, tools, or office furnishings, or equipment are damaged or stolen. In that case, a Business Owner’s Policy will get you back to work quickly by repairing or replacing your property.
Remember, if you have a BOP, general liability coverage is included, so you don’t need a separate GL policy.
4. Do you provide a service or regularly give advice?
If so, you need Professional Liability insurance. This is sometimes called errors and omissions or E&O coverage. It protects you from claims that you did something you shouldn’t have done (an error) or didn’t do something you should have done (an omission). You can be sued for just about anything, even if you haven’t made a mistake or the client didn’t follow your advice. And even a baseless lawsuit can be expensive to defend. Professional Liability coverage will pay your defense costs, as well as a settlement or judgment, on a covered claim.
5. Do you maintain a website or store sensitive data, like credit card or social security numbers or health information?
If so, you should have cyber insurance. Cyber insurance covers the costs associated with a hack or data breach, including ransomware demands. Equally important, your Hiscox cyber policy includes CyberClear Academy, a suite of training tools to help you and your employees prevent a cyber incident in the first place, as well as crisis management services from breach response experts.
6. Do you have employees?
Virtually every employer is required to have workers compensation coverage, which pays medical costs and lost wages for employees who are injured or become ill on the job. The fines for not having this coverage are significant, and an uninsured employer would have to pay an employee’s costs out of pocket, so this is crucial coverage for employers.
Having the right business insurance is critical to protecting the business you’ve worked so hard to build. Get a quote at Hiscox.com, and your business could be covered today.
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
In her latest blog, Amy Pal helps you develop your own clear guidelines around complimentary free employee services.
From managing air traffic on busy days to handling frustrated guests' complaints, your front desk team often serves as the salon's emotional shock absorber. From a customer service lesson from the DMV to a list of strategies for caring for your front line, our experts offer ideas for alleviating stress, celebrating wins, and setting goals.
According to the KIM Report, top-line salon revenue appears steady or slightly up, but that growth is driven primarily by service price increases. Beneath the surface, retail performance and client visit frequency (appointment drift) are under real pressure. In his latest blog, Alain Audet offers strategies for keeping your salon's retail sales strong.
Putting your family to work in the salon offers some real tax benefits, but you have you have to play by the rules of the tax code to claim them. Azarvand Tax Law's Leticia Skrabut, Esq., shows you how.
Discover how to create a true “WOW experience” for every client by first building a culture where your team feels engaged, empowered, and inspired. Drawing on Calvin Stovall’s Iconic Framework, this blog explores how salon, spa, and clinic leaders can strengthen culture, elevate customer experience, and build a business that stands out for the long term.
Sponsored by Phorest Salon Software
The wellness industry is growing fast, and salons and barbershops already are an important part of it. In her first blog, Tracy Rado shares where the wellness dollars are heading, and how salons can grow with this movement.
While salon sales are increasing, owners often feel they're working harder for the same or less profit. Leverage Q2 data from The KIM Report, Alain Audet reveals some of the structural changes that are dampening your growth and why your region and your salon size matters.
Weaknesses in your business are amplified during the Holiday Season. Spark Pro Global's Lucy Randall shows you five things to do now to have the strongest holiday season yet.

In Kati Whitledge's latest blog, she shares how salons have moved away from dress codes and embraced appearance standards. But by removing strict dress codes, some businesses may have unintentionally lowered their appearance standards. Whitledge helps you explain to your team why an appearance standard is important and how to smoothly implement a new appearance policy.
The Small Business Health Care Tax Credit is a non-refundable tax credit for for-profit businesses that provides a financial incentive for eligible employers who offer health insurance coverage to their employees. Leticia Skrabut, Esq., walks you through how to claim that credit.
Developing strong work habits early in one's career supports long-term success in the salon industry. Jesse Linares offers new stylists his top five tips.
Most salon owners have no idea what these numbers are. You can hit record sales and still have a profit problem. The difference comes down to four numbers almost nobody was taught to track.
Sponsored by Strata Salon Systems™
A five-area audit every owner-dependent salon needs to run. You built something that looks successful. Now find out if it can survive without you.
Sponsored by Strata Salon Systems™
Every month you put off fixing the problem, it gets bigger, more expensive, and harder to solve.
Sponsored by Strata Salon Systems™
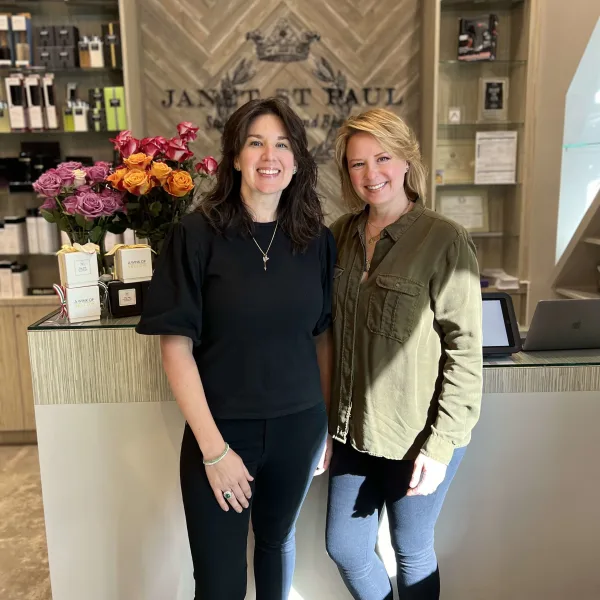
At Janet St. Paul Studio for Hair and Beauty, Director of Operations Natasha McMillen helps bring her wife Janet St. Paul's vision to life, elevating every system from education to operations.
Expand your color service menu with the Pinstripe technique. Brooks and Brooks' Marlon Hawkins walks you through the technique.