You Don't Own a Salon. You Own A Business.
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
 MENU
 SEARCH
Learn how to make the most of your hard-earned dollars from a financial adviser. Her three-step plan requires you to commit to saving, make it a habit and allocate wisely.
From NAILS Magazine Career Handbook.
With money’s familiarity, it’s easy to lose sight of its importance in your life today and—more importantly—in your future. Because of this, it’s often a good practice to put away debit and credit cards and use cash only to make money less intangible and more familiar.
However, in the beauty profession, the opposite is true. Because salons are a cash-based business, it is always available, and cash too becomes insubstantial and familiar. It becomes just as elusive as money spent with debit and credit cards.
Dollars become just pieces of paper, and you can easily fall into an easy-come-easy-go pattern of money management. But the earning of those dollars isn’t easy, and it’s a shame that this familiarity lulls you into unconscious behaviors where you don’t make the most of your money today, but more importantly, you don’t save your money for tomorrow.
So how do you change this unconscious pattern with money?
THREE STEPS TO FINANCIAL RESPONSIBILITY:
Commit to using your hard-earned dollars for both today and tomorrow.
Divide a sheet of paper down the middle. On the left side, list all the reasons why you don’t save now. On the right side, list the reasons why you want to save. Analyze the list and decide on which side you want to be—not where you think you should be, but rather where you want to be. A commitment needs to be your choice, not someone else’s. Once you choose, you will commit consciously to saving for the future instead of unconsciously spending for today.
Choose one day a week to contribute to your future.
Take the entire day’s earnings (or a portion) and deposit it into a separate savings account. Make this a weekly ritual that takes priority over everything. No excuses. After a month, it will become a habit that replaces your old pattern of spending.
Allocate for the future.
When you have $1,000 in your new account, you can allocate between short-term and long-term investments. Allocate a portion or percentage of the new account as a safety net for emergencies (six months to a year), a portion for larger, projected expenses (one to five years), and a portion for long-term investment (five years or more). It’s important to fund all three segments at the same time or you fall prey to never getting beyond the safety net portion. Once you have done the allocation, separate the money into three accounts, divide your weekly deposits in the same way and watch them grow.
These three easy steps are all it takes to set up a lifetime savings plan. You’ve made the commitment, formed a habit and allocated wisely.
Once your plan is underway, you’ll need to decide where to invest these dollars. There are many types of accounts. Here are a few points to consider:
Convenience. Because you are trying to make this a habit, set up your initial accounts where it is easy to make deposits. Remember, it won’t take much of an obstacle to end a habit. Make it easy to stay committed.
Fees. Because today’s savings accounts only pay about 1%, find accounts where monthly fees won’t eat up the earnings. Credit unions are often a great source for low fees.
Risk tolerance. As your money grows, there are more investment options for generating higher investment returns (earnings). Higher returns generally mean higher risk of loss. Don’t be talked into investments that keep you awake at night worrying. Find an investment with a comfortable level of risk.
Investment horizon. This refers to the length of time you expect your money to be invested. If you will use the money within a year, use a savings-type account where there is no risk for untimely fluctuations in value. But if you won’t be using the money for a long time, you can invest in something that has higher returns, more risk, and consequently more fluctuations. With a longer investment horizon, you can time the withdrawal of these dollars and not worry about having to do it on a bad market day.
Mutual funds. With more than 10,000 funds to choose from, you have a wide variety of investments to match your risk tolerance and investment horizon. Using mutual funds gives you the option to not put all your eggs in one basket. So even with only a small amount to invest, you can invest in small pieces of many stocks and bonds allowing you to diversify and spread out your risk.
Retirement plans. For long-term investments, take advantage of tax laws that allow you to defer and/or eliminate tax consequences. By doing so, you’re using government dollars to contribute to your future. There are many types of retirement plans to choose from. Consult your tax professional to find one that fits you best.
These are just some of the investment considerations ahead of you. Before you know it, your savings will grow into something to be proud of, and you’ll be on your way to financial freedom. Regardless of your age, today is the perfect day to begin a new conscious life with money.
To learn more about saving for retirement, visit nailsmag.com/retire.
Originally posted on Modern Salon
In his latest blog, Leon Alexander Ph.D., challenges industry conventional thinking to help owners add more to their bottom lines.
In her latest blog, Amy Pal helps you develop your own clear guidelines around complimentary free employee services.
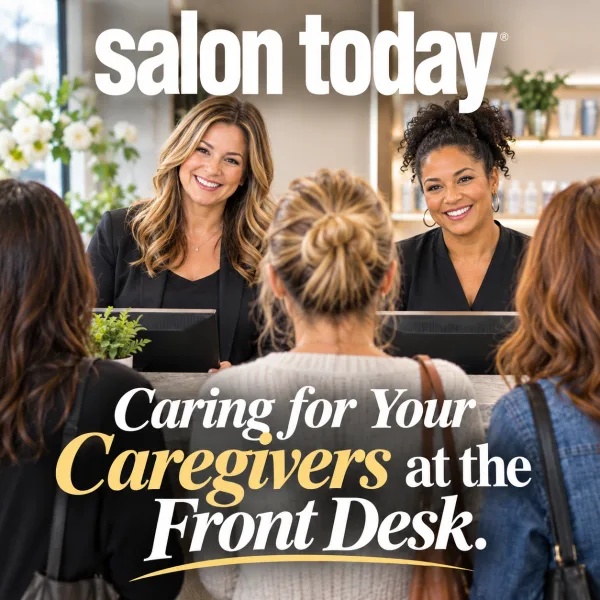
From managing air traffic on busy days to handling frustrated guests' complaints, your front desk team often serves as the salon's emotional shock absorber. From a customer service lesson from the DMV to a list of strategies for caring for your front line, our experts offer ideas for alleviating stress, celebrating wins, and setting goals.
According to the KIM Report, top-line salon revenue appears steady or slightly up, but that growth is driven primarily by service price increases. Beneath the surface, retail performance and client visit frequency (appointment drift) are under real pressure. In his latest blog, Alain Audet offers strategies for keeping your salon's retail sales strong.
Putting your family to work in the salon offers some real tax benefits, but you have you have to play by the rules of the tax code to claim them. Azarvand Tax Law's Leticia Skrabut, Esq., shows you how.
Discover how to create a true “WOW experience” for every client by first building a culture where your team feels engaged, empowered, and inspired. Drawing on Calvin Stovall’s Iconic Framework, this blog explores how salon, spa, and clinic leaders can strengthen culture, elevate customer experience, and build a business that stands out for the long term.
Sponsored by Phorest Salon Software
The wellness industry is growing fast, and salons and barbershops already are an important part of it. In her first blog, Tracy Rado shares where the wellness dollars are heading, and how salons can grow with this movement.
While salon sales are increasing, owners often feel they're working harder for the same or less profit. Leverage Q2 data from The KIM Report, Alain Audet reveals some of the structural changes that are dampening your growth and why your region and your salon size matters.
Weaknesses in your business are amplified during the Holiday Season. Spark Pro Global's Lucy Randall shows you five things to do now to have the strongest holiday season yet.

In Kati Whitledge's latest blog, she shares how salons have moved away from dress codes and embraced appearance standards. But by removing strict dress codes, some businesses may have unintentionally lowered their appearance standards. Whitledge helps you explain to your team why an appearance standard is important and how to smoothly implement a new appearance policy.
The Small Business Health Care Tax Credit is a non-refundable tax credit for for-profit businesses that provides a financial incentive for eligible employers who offer health insurance coverage to their employees. Leticia Skrabut, Esq., walks you through how to claim that credit.
Developing strong work habits early in one's career supports long-term success in the salon industry. Jesse Linares offers new stylists his top five tips.
Most salon owners have no idea what these numbers are. You can hit record sales and still have a profit problem. The difference comes down to four numbers almost nobody was taught to track.
Sponsored by Strata Salon Systems™
A five-area audit every owner-dependent salon needs to run. You built something that looks successful. Now find out if it can survive without you.
Sponsored by Strata Salon Systems™
Every month you put off fixing the problem, it gets bigger, more expensive, and harder to solve.
Sponsored by Strata Salon Systems™
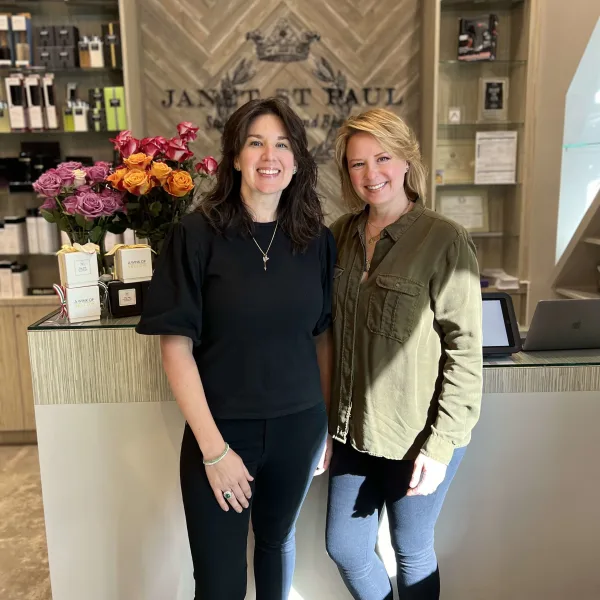
At Janet St. Paul Studio for Hair and Beauty, Director of Operations Natasha McMillen helps bring her wife Janet St. Paul's vision to life, elevating every system from education to operations.
Expand your color service menu with the Pinstripe technique. Brooks and Brooks' Marlon Hawkins walks you through the technique.