


5 Things Every New Stylist Should Learn Early
Developing strong work habits early in one's career supports long-term success in the salon industry. Jesse Linares offers new stylists his top five tips.
 MENU
 SEARCH
Eric Tyson, the author of Small Business Taxes for Dummies offers small business owners nine strategies for saving money on their taxes, which increases revenue.
If you’re a small business owner, you know: The quest for revenue is never-ending. That means, besides chasing new customers, you’re also scouring your expenses to see where you might make cuts. My suggestion? Focus on minimizing one of the biggest (and sneakiest) expenses you face. Taxes.
Quite often, small business owners overlook some great tax reduction opportunities. Yes, we all have to pay taxes, but there’s no reason to overpay. Employ legal tax reduction strategies, send less to Uncle Sam, and you’ll automatically keep more revenue for yourself.
Keep reading to learn nine things you can do this year to improve your tax situation:
Invest in wealth-building assets. During your working years, you probably don’t need or want taxable income from your investments, because it can significantly increase your income tax bill. So, I advise investing in real estate, stocks, and small business investments. These offer the best long-term growth potential. They are a tax-friendly option as well, because you’re in control and can decide when to sell and when to realize your profit.
Hint: As long as you can hold on to these investments for more than one year, your profit is taxed at the lower, long-term capital gains rate.
Fund some retirement accounts. When you funnel your savings dollars into retirement accounts, such as 401(k), 403(b), SEP-IRA, or SIMPLE IRA, you can earn substantial upfront tax breaks on your contributions.
If you think that saving for retirement is boring, just consider the tens of thousands of tax dollars these accounts can save you during your working years. And if you don’t take advantage of these accounts, you may well have to work many more years to accumulate the reserves necessary to retire.
Contribute to a health savings account. HSAs hold promise for people to put money away on a tax-advantaged basis to pay for healthcare-related expenses. Money contributed to an HSA is tax-deductible, and investment earnings compound without tax and aren’t taxed upon withdrawal so long as you use the funds to pay for eligible healthcare costs. So, unlike a retirement account, HSAs are actually triple tax-free!
Calculate whether a deduction is worth itemizing. The IRS gives you two methods of determining your total deductions. You can either choose the standard deduction method, or you can choose to itemize. Standard deductions make sense if you make a regular paycheck, have a rented apartment, and have no large expenses. In 2019, single people qualify for a $12,200 standard deduction, and married couples filing jointly get a $24,400 standard deduction.
The other deduction method is itemizing. This procedure is more of a hassle, but if you can tally up more than the standard deduction amount, itemizing saves you money. Your personal property and state income taxes are itemizable, up to an annual cap of $10,000. Further, if you pay a fee to the state to register and license your car, you can itemize the expenditure as a deduction. (However, you can deduct only the part of the fee that relates to the car’s value.) Because you can control when to pay particular expenses that are eligible for itemization, you can shift more of them into selected years to take full advantage of itemizing. However, if your itemized deductions are equal to or less than the standard deduction, take the standard deduction.
Trade consumer debt for mortgage debt. Suppose you own real estate but haven’t borrowed as much money as your lender allows. And suppose you’ve run up high-interest consumer debt. In that case, you may be able to refinance your mortgage (borrowing at a lower interest rate than your credit card bill) and pull out extra cash to pay off your consumer debt. You may even get a tax-deduction bonus, because while consumer debt isn’t tax-deductible, mortgage debt usually is.
Remember that refinancing your mortgage and establishing home equity lines involve fees and charges. Keep these expenses in mind when weighing the pros and cons of this strategy. Also, be aware that borrowing against the equity in your home can be an addictive habit that can handicap your ability to work toward other financial goals. Stay responsible.
Consider charitable contributions and expenses. When you itemize your deductions on Schedule A, you can deduct contributions made to charities. Most people already know that when they write a check to a college or house of worship, they can deduct it. Yet many taxpayers overlook the fact that they can also deduct expenses while performing activities for charitable organizations. For example, when you go to volunteer at a soup kitchen, you can deduct your transportation costs getting there. You can also deduct the fair market value of donations of clothing and other goods to charities; just keep your documentation of donated items. Finally, you can deduct contributions to local schools, including youth sports programs, as long as the money goes to the overall team rather than being earmarked for your child. You can even deduct the cost of driving your kids to school events.
Scour for self-employment expenses. If you’re self-employed, you already deduct a variety of expenses from your income before calculating the tax that you owe. When you buy a computer or office furniture, you can deduct those expenses. Employee salaries, office supplies, rent or mortgage interest for your office space, and phone expenses are also generally deductible.
Although more than a few business owners cheat on their taxes, some self-employed folks don’t take all the deductions they should. Be sure you take advantage of deductions for which you are eligible.
If you’re part of a married couple, crunch the numbers on filing separately. About 5 percent of married couples file their federal income tax returns under the status of “Married Filing Separately.” Most do so to save money, but there can be other reasons, such as each spouse not wanting to be liable for their spouse’s tax transgressions. To know if you should consider this option, crunch the numbers. Couples with the following characteristics may benefit:
If one spouse owns a pass-through business that is eligible for the 20 percent pass-through deduction but loses that deduction due to the combined income of their spouse.
If one spouse has high medical expenses, which can be written off when they exceed 7.5 percent of adjusted gross income, but loses that deduction due to the higher combined income with their spouse.
If the couple lives in a state that has a tax code that may favor spouses who file separately.
If you have a tax preparer, be careful to understand their additional fee for filing separate returns as that cost may wipe out the potential tax savings.
Consider working overseas. When you work in a foreign country with low income taxes, you may be able to save big-time on income taxes. For tax year 2019, you can exclude $105,900 of foreign-earned income (whether you work for a company or are self-employed) from U.S. income taxes. To qualify for this exclusion, you must work at least 330 days (about 11 months) of the year overseas or be a foreign resident. If you earn more than $105,900, don’t worry about being double taxed on income above this amount. You get to claim credits for foreign taxes paid on your U.S. tax return, and the IRS gives you two extra months, until June 15, to file your tax returns.
Remember two caveats to this exclusion. First, many of the countries people dream of living in—such as England, France, Italy, Sweden, Germany, and Spain—have higher income tax rates than the ones in the United States. Also, this tax break isn’t available to U.S. government workers overseas.
When you’re running a small business, every penny counts. Having more revenue in the bank can make the difference between struggling and thriving. A smart tax strategy can help more than you may have ever
# # #
About the Author: Eric Tyson, MBA, is the author of Small Business Taxes For Dummies®, Second Edition (available directly from Amazon by clicking on the title). Eric is an internationally acclaimed and best-selling personal finance author, counselor, and writer. He is the author of five national best-selling financial books including Investing For Dummies, Personal Finance For Dummies, and Home Buying Kit For Dummies. He has appeared on NBC’s Today show, ABC, CNBC, FOX News, PBS, and CNN, and has been interviewed on hundreds of radio shows and print publications.
Developing strong work habits early in one's career supports long-term success in the salon industry. Jesse Linares offers new stylists his top five tips.
Most salon owners have no idea what these numbers are. You can hit record sales and still have a profit problem. The difference comes down to four numbers almost nobody was taught to track.
Sponsored by Strata Salon Systems™
A five-area audit every owner-dependent salon needs to run. You built something that looks successful. Now find out if it can survive without you.
Sponsored by Strata Salon Systems™
Every month you put off fixing the problem, it gets bigger, more expensive, and harder to solve.
Sponsored by Strata Salon Systems™
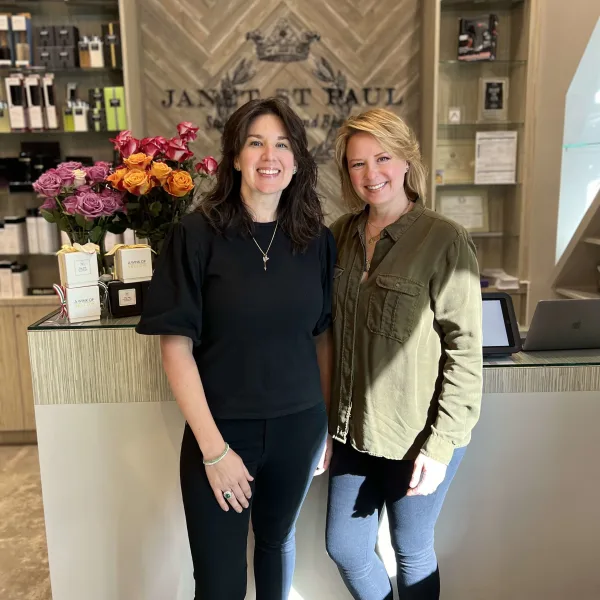
At Janet St. Paul Studio for Hair and Beauty, Director of Operations Natasha McMillen helps bring her wife Janet St. Paul's vision to life, elevating every system from education to operations.
Expand your color service menu with the Pinstripe technique. Brooks and Brooks' Marlon Hawkins walks you through the technique.
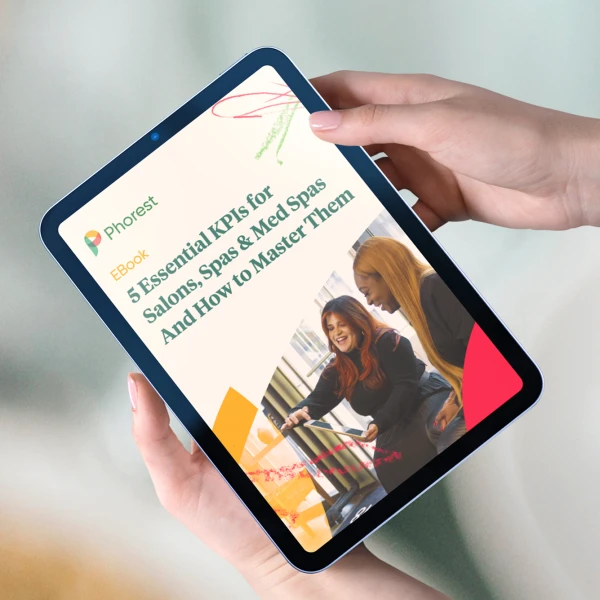
The strongest salons, spas, and med spas know which numbers tell the real story of their business. In this practical guide, Phorest breaks down the five essential KPIs every business should track to improve retention, boost revenue, and make smarter decisions with confidence.
Sponsored by Phorest
At Bella Style Salon in Slidell, Louisiana, Director of Operations Angela Meyer tackles inventory, team management, and guest relations. Read all about her in our latest Meet the Manager.
Starting at Impressions front desk in 2006 when he was 19 years old, General Manager Paul Petrowsky is a seasoned professional who owner Sarah Taylor says is responsible for much of her own success.
Planning is in full swing for the most anticipated events and promotions for the 2026 holidays. As owners share their favorite ways to celebrate, they prove that a carefully planned event can also build culture, increase client loyalty, boost sales, and set a business up for a successful 2027.
When things run amok at Mane Attraction Salon, Owners Chris and Jenny Knudsen say General Manager Sami Hernandez is their go-to resource and ultimate sounding board. Meet Sami in this installment of Meet the Manager.
Pagoda, a new AI-native operating system for scheduling, payments, patient records, marketing, and client communications, launches at Skinovatio Medical Spa in Arlington Heights, Illinois.
At a panel discussion hosted by L’Oréal Professionnel in Paris in early July, French Philosopher Sophie Galabru explored the cultural shift where women are increasingly choosing natural, personalized color results over traditional grey coverage. In an exclusive interview with SALON TODAY, Galabru and L’Oréal Professionnel Colorist Pierrick Beringer discuss this shift and how salons and colorists respond.
At Salon Blonde, Director of Operations treats the staff as the salon's most important guests, while her wonderful 'nerdy' side, loves data, systems, and numbers. Find out how she makes Salon Blonde tick.
In an exclusive interview with SALON TODAY, Salon Owner Salvatore Minardi reflects on his past 18 months as Intercoiffure America Canada's World Talent Exchange Ambassador and how his experiences will help encourage cultural and artistic exchange and support greater engagement between ICA and the global organization Intercoiffure Mondial.
Everything you need to know about client retention as a salon owner.
Owner Shelby Bills says her general manager, Sydney Osborne, reminds her of the power of leading with heart. Find out how Osborne became a great leader in our lastest installment of Meet the Manager.